How Much Is the Age Pension? Rates for Singles and Couples, Homeowners and Renters

Figures current from 20 September 2026. How this is made
Key takeaways
- The full Age Pension is $1,237.70 a fortnight for a single person - about $32,180 a year. A couple gets $933.00 each, or $1,866.00 between them.
- A couple gets about one and a half times the single rate, not double. Each partner gets about three-quarters of it.
- Renting doesn't change the rate. It raises how much you can own before the assets test starts to reduce the pension - $600,000 instead of $333,000 for a single person - and you may get Rent Assistance on top.
- Over the limit, the assets test cuts the pension by $3 a fortnight for every $1,000 (couple combined) - about $300 a fortnight for every $100,000. A homeowner couple keeps some pension up to $1,121,000 in assets.
- The rates change every 20 March and 20 September. These are the rates from 20 September 2026.
How much is the Age Pension? At the full rate, $1,237.70 a fortnight for a single person and $933.00 each for a couple. But how much of that you get depends on two things: whether you're single or a couple, and whether you own your home. This guide covers all four households, the limits that shrink the pension, and when the numbers change.

How much is the Age Pension in 2026?
These are the maximum rates from 20 September 2026, before tax. The full rate is really three payments rolled into one: the basic pension, the Pension Supplement and the Energy Supplement - two smaller top-ups paid on top of it.
| Per fortnight | Single | Couple, each | Couple, combined |
|---|---|---|---|
| Basic rate | $1,135.40 | $855.90 | $1,711.80 |
| Pension Supplement | $88.20 | $66.50 | $133.00 |
| Energy Supplement | $14.10 | $10.60 | $21.20 |
| Total | $1,237.70 | $933.00 | $1,866.00 |
Over a year, the full single rate comes to $32,180.20, and the full couple rate to $48,516.
The Age Pension is a taxable payment. Centrelink doesn't take tax out automatically, but it will if you ask.
When do the Age Pension rates change?
The Department of Social Services adjusts the rates every 20 March and 20 September. The assets test limits and cut-off points are reviewed in March, July and September. So whenever you see an Age Pension figure, check the date on it - including ours.
You can claim from the 13 weeks before you reach Age Pension age, which is 67. The pension isn't paid automatically - you have to claim it.
How much can you have and still get the full pension?
The Age Pension has two means tests: an assets test (what you own) and an income test (what you earn, or are assumed to earn). The assets test only applies if it gives a lower rate than the income test - so in effect, you're paid on whichever gives you less. Here are the assets test limits for all four households.
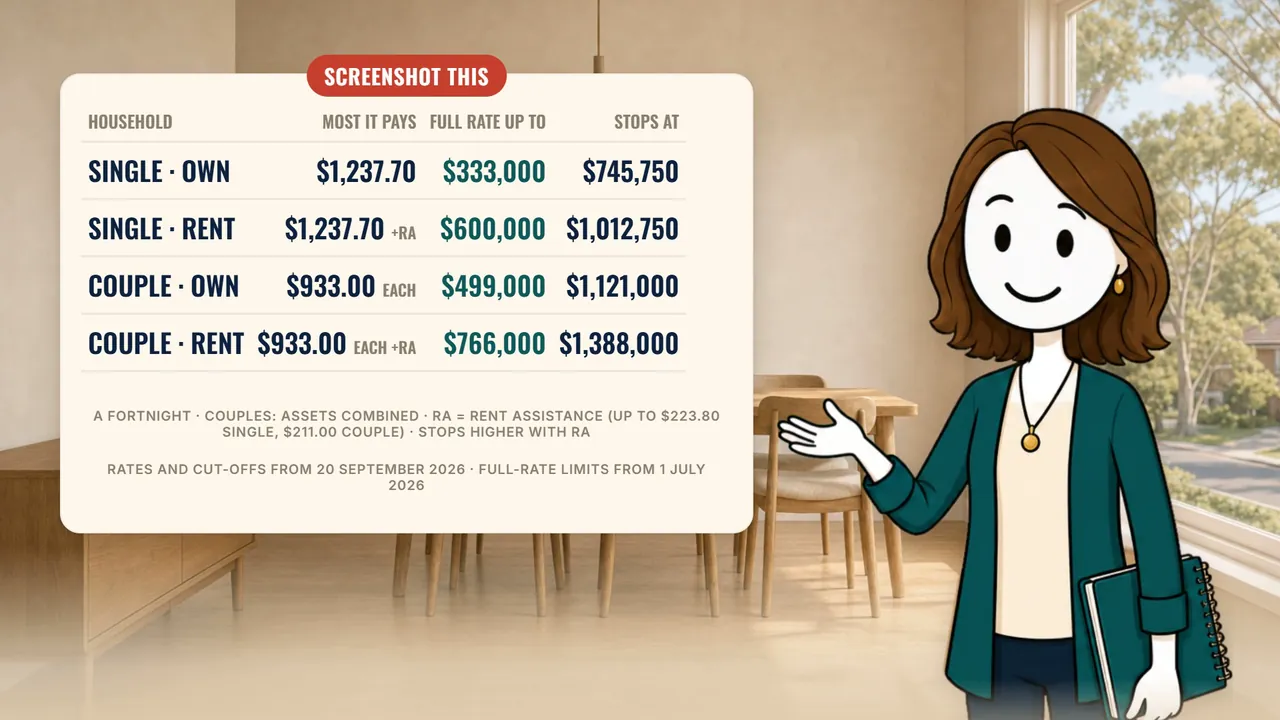
| Household | Full pension up to | Part pension stops at |
|---|---|---|
| Single, homeowner | $333,000 | $745,750 |
| Single, renter | $600,000 | $1,012,750 |
| Couple, homeowner (combined) | $499,000 | $1,121,000 |
| Couple, renter (combined) | $766,000 | $1,388,000 |
Your home and up to 2 hectares of land it's on aren't counted. Almost everything else is: savings, shares, the car, furniture at what it would sell for, and your super once you reach Age Pension age (or earlier, if it's paying you a pension). (Our guide to the Age Pension assets test has the full list.)
Over the limit, the pension shrinks slowly
Above the full-pension limit, your pension drops by $3 a fortnight for every $1,000 of assets over it (for a couple, $3 off the two pensions combined). That works out to about $300 a fortnight for every $100,000 over - a handy shortcut for a rough estimate.
Say you're a single homeowner with $433,000 of assessable assets - $403,000 in savings plus $30,000 of car and contents, so $100,000 over the limit:
- The assets test takes off 400 whole lots of $250, at $19.50 a year each: $7,800 a year, or $300 a fortnight.
- That leaves $937.70 a fortnight.
- On the income test, the same savings would pay more - about $1,086 a fortnight. So the assets test is the one that counts, and you get $937.70.
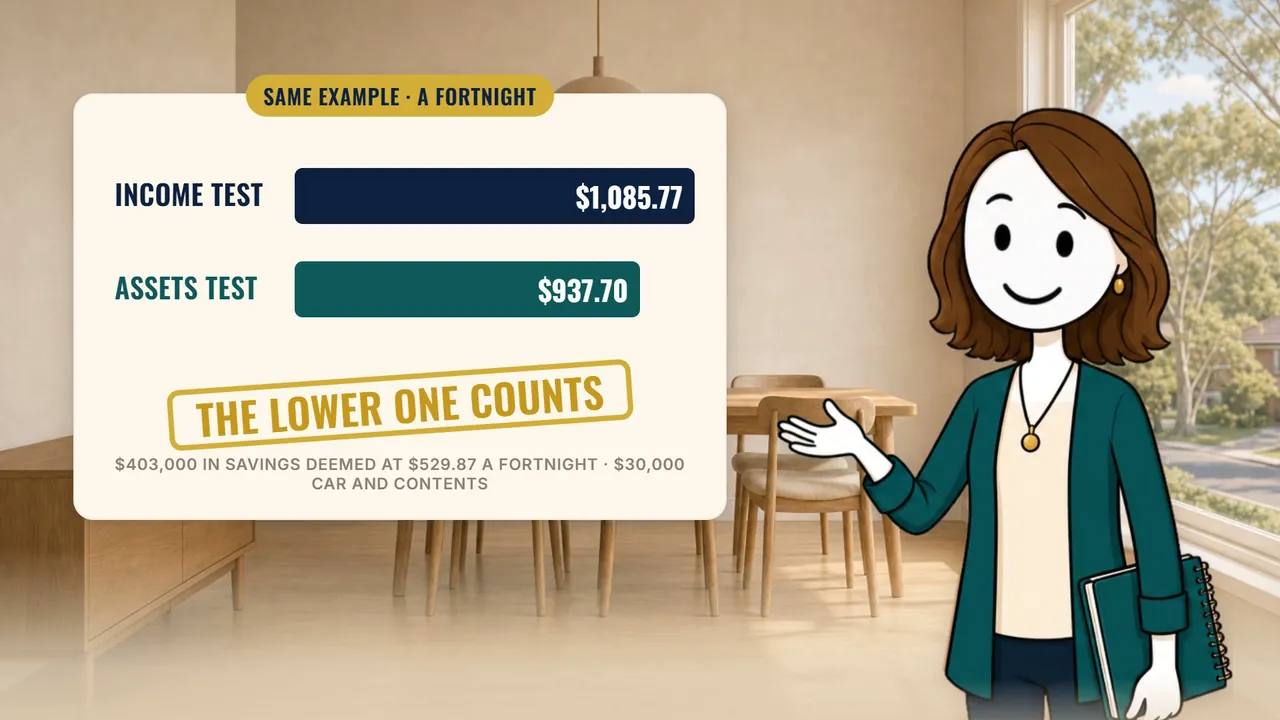
It's a slope, not a cliff. A single homeowner can have more than double the full-pension limit and still get something.
How much Age Pension does a renter get?
The rate itself is exactly the same - renting doesn't change it. What changes is how much you can own. For a single renter, the assets test allows the full pension with up to $600,000 of assets, not $333,000.
On top of that, if you rent privately you may get Rent Assistance. It pays 75 cents for every dollar of rent above a minimum, up to a cap:
| Per fortnight | Rent must be more than | Maximum reached at rent of | Maximum Rent Assistance |
|---|---|---|---|
| Single | $157.80 | $456.20 | $223.80 |
| Single, sharer | $157.80 | $356.74 | $149.20 |
| Couple, combined | $255.80 | $537.14 | $211.00 |
The sharer rate applies to a single person with no dependent children who lives in shared private accommodation and gets one of the listed payments - the Age Pension is one of them.
Who counts as a homeowner?
Owning a house isn't enough - it has to be the home you live in. Real estate you rent out, leave empty, or let someone else live in for free is counted as an asset.
Retirement villages depend on what you paid to move in. If your entry fee was more than the extra allowable amount - the gap between the homeowner and non-homeowner limits, $267,000 - you're treated as a homeowner and the fee isn't counted. If it was that amount or less, you're a non-homeowner: the fee is counted, and you may get Rent Assistance.
How much Age Pension does a couple get?
A couple gets $933.00 each, about three-quarters of the single rate. Together that's $1,866.00 a fortnight - about one and a half times a single pension, not two.
For a couple, almost everything is combined:
- Assets: one combined limit - $499,000 for homeowners, up to a cut-off of $1,121,000. That's how a homeowner couple can have more than a million dollars and still get some Age Pension.
- Income: the couple income test uses your combined income. So if one of you is still working, those wages can reduce the pension.
- A younger partner: if your partner is under Age Pension age and their super isn't paying them a pension, Centrelink doesn't count it yet. Only the partner who is 67 or over can be paid the Age Pension.

What a typical couple actually gets
Robyn and her husband are both 68 and own their home. They're an illustration, not real people. He retired with the men's median super balance for ages 60 to 64 ($236,126), she with the women's ($174,655) - so they have $410,781 in super between them, plus $30,000 of car and contents.
- Assets: $440,781 - under the couple limit of $499,000. The assets test pays the full rate.
- Income: Centrelink uses deeming - it assumes their super earns a set rate, explained below - and counts $13,192.29 a year, or $507.40 a fortnight.
- That's $111.40 a fortnight over the $396 couple free area - the income a couple can have before the pension starts to fall. Their combined pension drops by half of that: $55.70.
- Combined pension: $1,810.30 a fortnight - $905.15 each, or $47,067.80 a year.
- Add the 5% minimum drawdown from their account-based pensions ($20,539.05) and they live on about $67,600 a year.
That's about 86% of the way to ASFA's comfortable budget for a homeowner couple aged 65 to 84 ($78,998 a year, June quarter 2026). ASFA's comfortable and modest budgets are for people who own their home; it publishes a separate modest budget for renters. The pension is the bigger share of their income. (The medians are for people with a super account, ATO data at June 2024.)
When a couple becomes a single
Now say Robyn's husband dies and all his super passes to her. Centrelink now treats her as single. Her single rate is higher than her half of the couple rate - but she's now measured against the single limit.
- Her assets are still $440,781. As a single homeowner, that's $107,781 over the $333,000 limit.
- The assets test takes off 431 whole lots of $250, at $19.50 a year each - $323.25 a fortnight.
- On the income test she'd get about $1,080 a fortnight, so the assets test sets her rate: $914.45 a fortnight - about half the $1,810.30 the two of them got together.
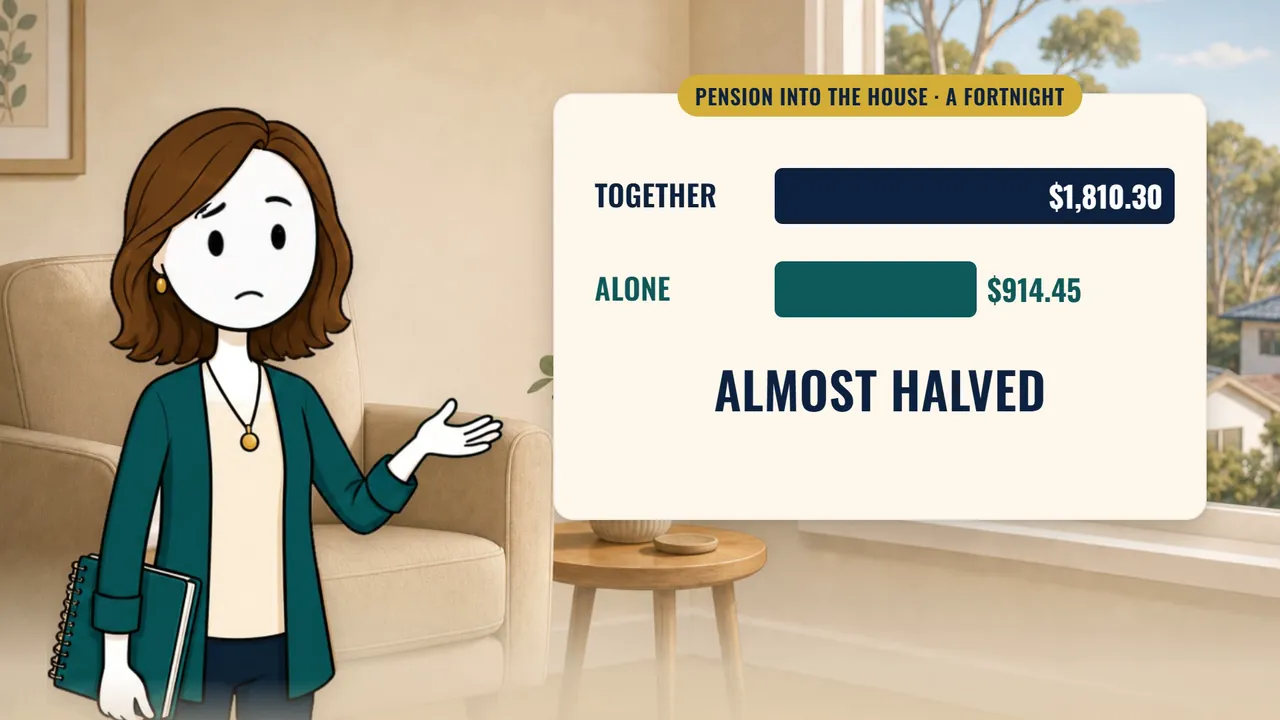
The bills don't halve. On ASFA's budgets, a single homeowner's comfortable retirement costs about 71% of a couple's. If both partners were getting a pension, Services Australia may pay a bereavement payment - usually the difference between the couple amount and the new single rate, over 14 weeks from the date of death.
There's another situation where each partner can get the single rate. If illness or infirmity means you can't live together in your home, and that's likely to continue indefinitely - permanent residential aged care is one example - you can be treated as a couple separated by illness. You're still assessed on your combined income and assets, against higher cut-offs, but each of you can be paid up to the single rate of $1,237.70.
The income test: why you might not get the full rate
Being under the assets limit doesn't guarantee the full pension. The income test can bite first.
Centrelink doesn't look at what your savings actually earn. It uses deeming - it assumes your financial assets earn a set rate (Services Australia's deeming page):
| Deeming from 20 September 2026 | Lower rate 1.75% on the first | Higher rate 3.75% on the rest |
|---|---|---|
| Single | $66,800 | above $66,800 |
| Couple, at least one on a pension | $110,600 combined | above $110,600 |
If your money earns more than that, the extra isn't counted. If it earns less, you're still assessed on the deemed amount.
Your deemed income is added to any other income. Above the free area - $226 a fortnight single, $396 for a couple combined - the pension drops by 50 cents for every dollar for a single person, and 25 cents each for a couple.
Wages are treated more gently. The Work Bonus sets aside $300 a fortnight of work income before the income test applies, and if you don't work, the unused amount builds up to a balance of $11,800.
What comes with the Age Pension
Services Australia automatically sends a Pensioner Concession Card to people who get the Age Pension. It means cheaper medicines, bulk-billed doctor visits and help with hearing services. If you're Age Pension age but don't qualify for the pension, the Commonwealth Seniors Health Card may still be available - it has an income test but no assets test.
A small group are paid differently. Some people who were on a part pension on 19 September 2009 are on a transitional rate: a maximum of $997.00 a fortnight single or $804.40 each for a couple, including the Energy Supplement.
The 20 September 2026 increase

The 20 September 2026 indexation lifted the rates above. One rule is worth knowing if you travel: the Pension Supplement stops after 12 weeks of short-term travel outside Australia, or immediately if you leave Australia to live in another country. The Age Pension itself has its own travel rules - and if you're thinking of retiring abroad, our comparison of the Age Pension with the UK, US and NZ pensions looks at what each country pays.
The bottom line
Single or couple sets the rate. Owning or renting sets how much you can have. And above the limit, the pension doesn't fall off a cliff - it shrinks slowly, and often lasts longer than people expect.
To see these rules applied to a typical super balance, read what the average Australian retires with. For your own estimate, Services Australia's online Payment Finder will work it out from your details, and its Financial Information Service is free - call the Older Australians line on 132 300 and ask for a FIS officer.
Frequently asked questions
My partner is younger and still works part-time. How does that affect my pension?
Only the partner who has reached Age Pension age can be paid, at the partnered rate - up to $933.00 a fortnight. Centrelink assesses both partners' income from all sources, so your partner's wages count in the couple income test. Your partner's super isn't counted while they're under Age Pension age and it isn't paying them a pension. Assets are assessed against the couple limits.
Do I have to report every time my savings go up?
You need to tell Centrelink if the value of your assets rises by $2,000 or more for financial assets, or $1,000 or more for other assets. You don't need to report market movements in listed shares, market-linked managed investments or account-based income streams - Centrelink revalues those itself.
I'm under the assets limit. Why don't I get the full $1,237.70?
Because the income test can pay less. If you have a moderate amount in savings or super, deeming can put your assumed income over the $226 free area (single), and the pension drops by 50 cents for each dollar over. The assets test only applies when it gives a lower rate than the income test.
Does an overseas pension reduce my Age Pension?
It may. Services Australia says income from, or assets outside, Australia may affect your rate. Our article comparing the Age Pension with the UK, US and NZ pensions covers how a UK pension is treated.
Sources
- Services Australia - How much Age Pension you can get - normal and transitional rates from 20 September 2026
- Services Australia - Assets test for Age Pension - full-pension limits and cut-offs (from 20 September 2026)
- Services Australia - Income test for Age Pension - free areas $226 / $396, tapers and cut-offs
- Services Australia - Deeming - 1.75% / 3.75%; thresholds $66,800 and $110,600
- DSS Social Security Guide 4.2.3 - the assets test reduction ($19.50 a year per $250; $3 a fortnight per $1,000) and when it applies
- DSS Social Security Guide 2.2.5.60 - illness separated couples
- Services Australia - How much Rent Assistance you can get - rates from 20 September 2026
- Services Australia - Real estate assets - principal home and retirement villages
- Services Australia - How the Work Bonus works - $300 a fortnight, $11,800 balance
- Services Australia - Who can get a Pensioner Concession Card
- Services Australia - Commonwealth Seniors Health Card income test
- Services Australia - What help there is when an adult dies - bereavement payment
- Services Australia - Travel outside Australia rules for Pension Supplement
- Services Australia - Who can get Age Pension and How to claim - age 67, claim up to 13 weeks before
- ASFA Retirement Standard - June quarter 2026 budgets (checked 3 November 2026)
- ASFA - An update on superannuation account balances (2026 edition) - median balances at 60 to 64, ATO data at June 2024
- ATO - Payments from super - 5% minimum drawdown at 65 to 74
General information only. This article is general information only. It doesn't take into account your objectives, financial situation or needs, and it isn't personal financial advice. Speak with a licensed financial adviser about your own situation. Services Australia's Financial Information Service (132 300) is free. Figures are current from 20 September 2026 and change every March, July and September - check servicesaustralia.gov.au and ato.gov.au for the latest.
A note on how this is made: Every article starts with real research and is checked against current ATO and Services Australia figures - that part isn't automated. AI tools help draft the text and produce the video's narration and visuals. We write, verify and stand behind every word.
Keep reading
- Average Super Balance at Retirement in Australia - and What the Age Pension Adds
- The Age Pension Assets Test: What Counts, Where the Pension Stops, and Whether Losing It Matters
- Average Super Balance by Age in Australia: 55, 60, 65 and 70 - and What the Age Pension Adds
New here? Start with the complete guide: Retirement in Australia, explained - every rule, every test and a countdown to your last working day.
More Age Pension
- When Only One Partner Is Eligible for the Age Pension: What an Age-Gap Couple Gets
- How to Boost Your Age Pension, Legally: Four Ways and the One That Backfires
- How Much Can You Have and Still Get the Full Age Pension? The Income Test and Deeming
- The Age Pension Assets Test: What Counts, Where the Pension Stops, and Whether Losing It Matters